

Budget App — PocketGuard

- 1.16K Reviews
- 4.5
- Downloads
- 100,000+
Our take on Budget App — PocketGuard from Appgk
I tend to distrust budgeting apps that promise to fix money problems with one glance at a colorful dashboard. A useful finance tool has to do something more practical: help me understand what is available, notice where it is going, and make the next decision easier. PocketGuard fits that role best when I treat it as a regular money check-in rather than a magic savings button. It is a free finance app from PocketGuard, Inc. with a 4.5 average from around 2.9 thousand ratings, and it is aimed at people who want spending, income, expenses, and saving goals in one place.
After using it as a budgeting companion, my impression is fairly clear. The app is approachable for someone who wants structure without building a spreadsheet from scratch, but it still rewards careful setup. The first view can feel reassuring because it turns several financial details into a simpler picture. The real value appears later, when I return to the same routine, check upcoming commitments, and use the available-money figure as a prompt to pause before spending.
How I built a dependable PocketGuard routine
My preferred starting point is deliberately boring. I first make sure income and recurring expenses are represented correctly, then I look at ordinary spending instead of trying to redesign my entire financial life in one sitting. That order matters because a budget can look precise while being based on incomplete or poorly understood information. PocketGuard works better when I give it a realistic baseline.
The central workflow is simple: review money coming in, account for fixed obligations, observe day-to-day spending, and decide what can safely remain available. I do not interpret that last figure as permission to spend everything immediately. I use it as a conversation starter with myself. If the amount seems unexpectedly high, I investigate. If it seems low, I look for a bill, purchase, or category that explains the change.
Best Parts of Budget App — PocketGuard
Things to Keep in Mind About Budget App — PocketGuard
This makes the app particularly useful for people whose main problem is awareness. I know how easy it is to remember rent and a phone bill while mentally losing track of small purchases, irregular subscriptions, or several trips to the same shop. A budgeting screen cannot remove those costs, but it can make the pattern harder to ignore. That is a more realistic benefit than expecting the app to make every financial decision automatically.
A practical everyday example is a week before payday. I might see a balance that looks comfortable, then remember that groceries, transport, and a scheduled payment still have to come from it. Instead of asking whether I can afford one more purchase in isolation, I check the broader picture first. That small pause is where PocketGuard earns its place: it changes the question from “Is there money in the account?” to “What does this money already need to do?”
News and Features Related to Budget App — PocketGuard

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
I also recommend giving the app a short observation period before judging its usefulness. The first session tells me whether the layout feels understandable, but repeated use tells me whether I will actually open it before spending. A budget app that is theoretically powerful but abandoned after two days is less useful than a modest tool that becomes part of my weekly routine.
The setup choices that deserve attention
Settings are not decoration in a finance app. They determine whether the information feels trustworthy. I would check income details, recurring expenses, categories, and any saving intention before relying heavily on the headline number. If a regular cost is missing, the app may give me a more optimistic view than my real month deserves. If something is entered twice, the opposite problem appears.
Don't want to read the full review?
My strongest setup habit is to separate fixed commitments from flexible spending in my own thinking, even when I am simply reviewing the app’s presentation. Fixed commitments are the costs that must happen; flexible spending is where I have room to adjust. This distinction helps me avoid cutting the wrong thing. If the budget feels tight, I would rather identify a controllable category than pretend a necessary bill can be negotiated away.
Categories deserve a second look after the first few days. Broad labels can be convenient, but they may hide a useful pattern. For example, several purchases that all feel harmless may add up to a category that deserves a weekly limit in my personal plan. On the other hand, over-categorizing every transaction can make the process tiring. I aim for enough detail to support a decision, not so much detail that reviewing money becomes another chore.
Screenshots
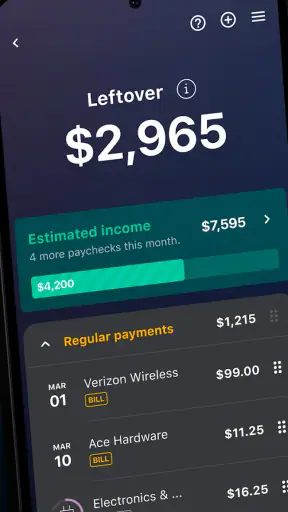
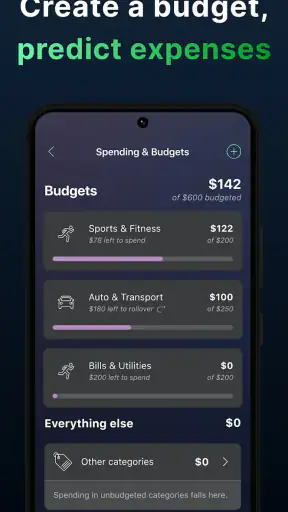
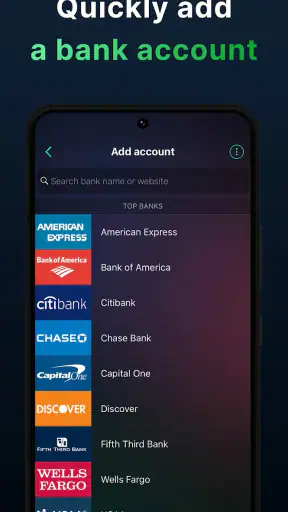
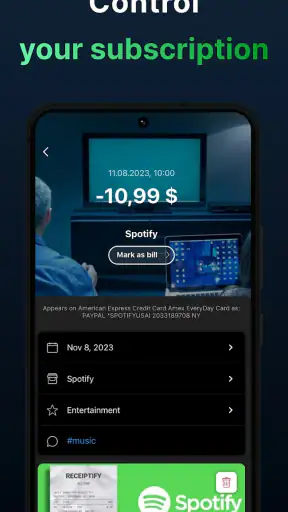
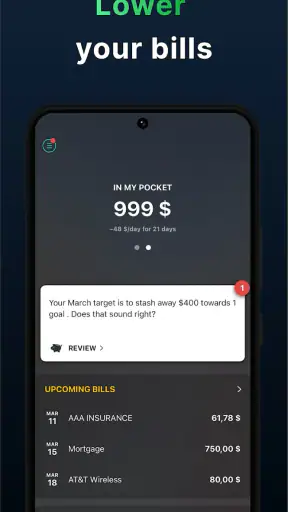
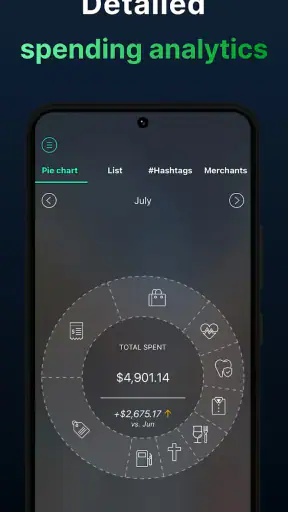
The most important setting is the one that makes the app reflect my actual month, not my ideal month. I would include less glamorous obligations before adding ambitious saving targets. That gives the budget a stable foundation. Once the ordinary bills and spending habits are visible, a saving goal becomes more believable because it is based on what remains after real life rather than on wishful arithmetic.
Privacy and account comfort also influence whether I would keep using it. PocketGuard is designed as a connected budgeting experience, so anyone who prefers entering every transaction manually should think about that workflow before committing. I personally find automation convenient when I want an up-to-date overview, but I would still review the result rather than assuming every item has been interpreted perfectly. Convenience reduces effort; it does not remove the need for judgment.
The app is free to install, while optional in-app purchases range from under a dollar to around one hundred and fifty dollars per item. That makes it sensible to begin with the free experience and decide whether the extra value matches my habits before paying. I would not upgrade simply because more controls exist. I would upgrade only if a particular paid capability solves a problem I repeatedly encounter.
Shortcuts that make the routine stick
The fastest users I know do not stare at their budgets for an hour. They create repeatable moments for checking them. I would open PocketGuard at the start of the week, after a major payment, and before an unusually expensive day. Those checkpoints are more useful than refreshing the app constantly because each one answers a specific question: What changed? What is still due? What can I safely spend?
Another effective pattern is to review transactions in batches. Instead of interrupting every purchase with a detailed analysis, I would set aside a few minutes to scan recent activity, correct anything that looks wrong, and notice categories that are drifting. This keeps the app from becoming a source of constant financial anxiety while still catching mistakes early enough to matter.
I also like pairing the app with a simple rule outside the app. For example, when I am considering a nonessential purchase, I check the available picture first and then wait until the next planned review if the purchase is not urgent. PocketGuard does not need to make that decision for me. Its job is to provide enough context for my own rule to work.
For households, the useful question is not only whether the numbers are visible but whether both people follow the same interpretation. One person may see a remaining amount as free spending money, while the other already has groceries and transport mentally assigned to it. I would agree on what the app’s figures mean before using them to settle disagreements. A shared tool cannot replace a shared definition of “available.”
People paid on an irregular schedule can also use the app, but they need more caution. I would avoid treating a strong month as the new normal. Instead, I would build decisions around the least dependable income I expect and treat unusually good months as opportunities to strengthen savings or cover future obligations. The app can organize the picture, but it cannot make variable income predictable.
Where PocketGuard is strong, and where it asks for patience
Compared with a spreadsheet, PocketGuard is easier to revisit because the budgeting experience is built around an app rather than a blank grid. I do not have to design formulas or decide how to present every figure before I can begin. That is a real advantage for someone who understands the need for a budget but has never enjoyed maintaining one.
Compared with a plain banking app, it encourages a wider view. A bank application is excellent for checking an account or making a payment, but it may not prompt me to think about the month as a whole. PocketGuard’s budgeting focus makes the relationship between income, obligations, spending, and saving more visible. I would still use my bank for banking tasks; I see this app as a layer for interpretation and planning.
Compared with an envelope-style method, PocketGuard may feel less tangible for people who need strict permission-based spending. Physical or digital envelopes make it obvious that money assigned to one purpose should not casually move to another. PocketGuard is better suited to users who want an overview and guidance rather than a rigid set of separate containers. If I routinely overspend because I treat every remaining balance as spendable, an envelope system may be the better fit.
There is also a trade-off between automation and control. Automated information can save time and make the overview more current, but it can encourage passive trust. I would inspect unusual entries, check that recurring costs make sense, and avoid making a major financial decision from one screen without understanding the underlying items. The app is most helpful when it shortens review time, not when it replaces review entirely.
Another limitation is behavioral rather than technical: PocketGuard cannot know which expenses matter most to me. It may show that a category is growing, but I still have to decide whether that spending is necessary, enjoyable, avoidable, or connected to a larger priority. A person looking for personalized financial advice, investment analysis, or detailed debt strategy may need a more specialized service alongside this budgeting tool.
Who should use it and who should look elsewhere
I would recommend PocketGuard to someone who wants a clear starting point for personal budgeting, especially if the alternative is ignoring finances or maintaining a spreadsheet that never gets updated. It is also a good match for users who like seeing income and expenses together and want a recurring habit built around checking what remains after obligations.
I would be more cautious recommending it to someone who wants total manual control over every entry, dislikes connected financial workflows, or needs a highly customized accounting system. A spreadsheet can be shaped around unusual circumstances, business expenses, multiple currencies, or detailed household rules in ways a streamlined budgeting app may not match. Likewise, a specialist debt or investment app may be more appropriate when budgeting is only one part of a larger financial plan.
The age rating is Everyone, which fits the app’s everyday money-management purpose. It is available for Android with a minimum operating system requirement of version eight or newer, and the current version is 5.19.3. The app has been available since March 16, 2016, and its audience has grown beyond a small experiment, with over one hundred thousand installs. Those details make it feel like an established option for basic budgeting rather than a brand-new tool I would approach without context.
Still, popularity would not be my deciding factor. I would choose it because the workflow is understandable and because I can imagine opening it at the moments when money decisions actually happen. If I already have a budgeting method that I follow faithfully, switching may add friction without adding much insight. The best reason to adopt PocketGuard is not that it contains every possible finance feature; it is that it can make a neglected routine easier to begin.
My verdict after turning it into a habit
PocketGuard is most effective when I use it as a decision checkpoint, not as an automatic financial referee. The app brings the important parts of a personal budget into a more approachable routine, and its free starting point lowers the risk of trying it. The developer, PocketGuard, Inc., has built something that speaks to ordinary budgeting problems: unclear spending, forgotten commitments, and the feeling that money disappears before the month is over.
My recommended approach is to set it up carefully, verify the recurring picture, review categories in batches, and create a few fixed moments for checking the app. I would begin without paying, use the free experience long enough to understand my own workflow, and consider an in-app purchase only when I can name the repeated inconvenience it would solve. That keeps the tool in service of my habits instead of letting the subscription decision become the focus.
The final question is whether it changes behavior. For me, it does when I use the available-money view to slow down a purchase, investigate an unexpected change, or protect money for a known obligation. It does less when I open it without a question and simply admire the summary. If you want a friendly budgeting companion and are willing to check the details behind the headline figures, I think PocketGuard is worth trying. If you need rigid envelopes, deep customization, or specialist financial planning, I would choose a more focused alternative.
Budget App — PocketGuard FAQ
What is PocketGuard, and how does it help manage a budget?
PocketGuard is a personal finance and budgeting app designed to give you a clearer view of your money. After connecting eligible financial accounts, it can organize balances, income, bills, and spending in one place. Its main feature is the “In My Pocket” style overview, which estimates how much money may remain available after accounting for recurring expenses, savings goals, and everyday spending.
Is PocketGuard safe to use with bank and financial accounts?
PocketGuard uses security measures intended to protect the financial information you provide, and account connections are generally handled through secure financial-data services rather than by sharing your online banking password directly with the app. However, no online service is completely risk-free. Before connecting an account, review PocketGuard’s current privacy policy, security information, supported institutions, and the permissions requested on your device.
Does PocketGuard cost money, or is there a free version?
PocketGuard may offer both free and paid features, but the exact availability, pricing, and subscription options can vary by platform, country, and current promotion. Basic budgeting tools may be accessible without payment, while advanced features—such as enhanced planning, customization, or additional financial insights—can require a subscription. Check the in-app pricing page before starting a trial, and review renewal terms carefully.
Which financial accounts can I connect to PocketGuard?
PocketGuard supports connections to many common financial institutions, but coverage is not universal and can change over time. Depending on your location, you may be able to link checking and savings accounts, credit cards, loans, and other supported accounts. Search for your bank during setup before committing to the app. If an institution is unavailable, some information may need to be entered or tracked manually.
Is PocketGuard suitable for beginners, and can it replace a financial adviser?
PocketGuard is generally suitable for beginners who want a straightforward overview of income, bills, spending, and available cash. Its automated categorization and budget summaries can reduce the effort involved in tracking finances, although categories may occasionally need correction. The app is a budgeting tool, not a substitute for a qualified financial adviser, tax professional, or personalized investment guidance.











